Advertisements
Top weekly article
Светлая сторона крипты
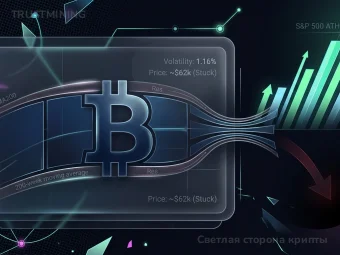
Ветры зимы в криптосфере
Почему биткоин застрял на месте, пока фондовый рынок бьет рекорды

Tax rate is the percentage, fixed amount, or other rate applied to a relevant tax base to determine a tax liability.
For mining activity, the applicable rate depends on the jurisdiction, taxpayer status, business structure, and type of tax. A single universal mining tax rate therefore cannot be applied to all mining operations.
Nominal and effective tax burden
The nominal tax rate does not necessarily equal the effective tax burden. Deductions, exemptions, tax credits, expenses, and rules for determining the tax base can change the final amount payable.
When modeling mining economics, the tax rate should be applied only to the tax base defined by the relevant legislation.
Taxes can affect net profit, cash flow, and the calculated payback period of a mining project.
Popular models

Brands


Fluminer

ElphaPex

Ebang

Canaan

Todek

Bitdeer

iPollo

Baikal

StrongU

VolcMiner

MicroBT

Lucky Miner

Jasminer

Auradine

Innosilicon

IceRiver

Hummer Miner

Holic

Heatbit

Goldshell

FusionSilicon

Bitaxe

Bitfily

Digital Shovel

Dayun

Bolon Miner

Braiins

BW

Halong Mining

Bitfury

Spondoolies

PinIdea

Pantech

Obelisk

DragonBall Miner

FFMiner

ForestMiner

GMO miner