Advertisements
Top weekly article
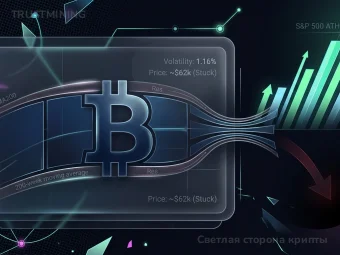
Светлая сторона крипты
Ветры зимы в криптосфере
Почему биткоин застрял на месте, пока фондовый рынок бьет рекорды

Depreciation is the allocation of the cost of a long-term asset across the periods in which the asset is used. In mining economics, it helps reflect the fact that equipment has a limited useful life and may lose economic value over time.
Depreciation does not necessarily represent a cash payment at the moment it is recorded. This distinguishes it from direct cash expenses such as electricity payments.
Depreciation in mining models
The cost of equipment can be allocated over an estimated useful life. The resulting amount depends on the original cost, useful life, residual value, and depreciation method.
For mining equipment, economic useful life may be shorter than physical operating life because newer generations can provide substantially better efficiency and network conditions can change.
Depreciation is closely related to equipment depreciation, while the broader term can also apply to other long-term infrastructure assets.
Popular models

Brands


Fluminer

ElphaPex

Ebang

Canaan

Todek

Bitdeer

iPollo

Baikal

StrongU

VolcMiner

MicroBT

Lucky Miner

Jasminer

Auradine

Innosilicon

IceRiver

Hummer Miner

Holic

Heatbit

Goldshell

FusionSilicon

Bitaxe

Bitfily

Digital Shovel

Dayun

Bolon Miner

Braiins

BW

Halong Mining

Bitfury

Spondoolies

PinIdea

Pantech

Obelisk

DragonBall Miner

FFMiner

ForestMiner

GMO miner