Advertisements
Top weekly article
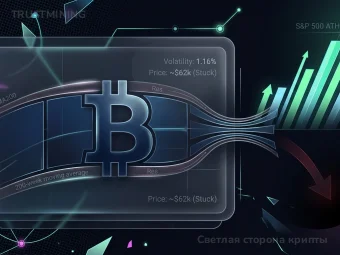
Светлая сторона крипты
Ветры зимы в криптосфере
Почему биткоин застрял на месте, пока фондовый рынок бьет рекорды

Slippage is the difference between the price a trader expected when placing an order and the actual execution price or average execution price.
Slippage commonly occurs when large market orders consume multiple price levels, when liquidity is limited, or when the market moves rapidly.
Example
Suppose the best available BTC sell price is $60,000, but only a small amount is available there. A large market buy order may execute at $60,000, then $60,020, $60,050, and higher levels. The resulting average price is higher than the initially displayed price.
Slippage depends on order size, order-book depth, volatility, and how quickly market prices are changing.
Reducing slippage
- use limit orders when appropriate;
- split large orders into smaller parts;
- trade on more liquid markets;
- check market depth before placing large orders.
Popular models

Brands


Fluminer

ElphaPex

Ebang

Canaan

Todek

Bitdeer

iPollo

Baikal

StrongU

VolcMiner

MicroBT

Lucky Miner

Jasminer

Auradine

Innosilicon

IceRiver

Hummer Miner

Holic

Heatbit

Goldshell

FusionSilicon

Bitaxe

Bitfily

Digital Shovel

Dayun

Bolon Miner

Braiins

BW

Halong Mining

Bitfury

Spondoolies

PinIdea

Pantech

Obelisk

DragonBall Miner

FFMiner

ForestMiner

GMO miner